Khyati Mashru Vasani
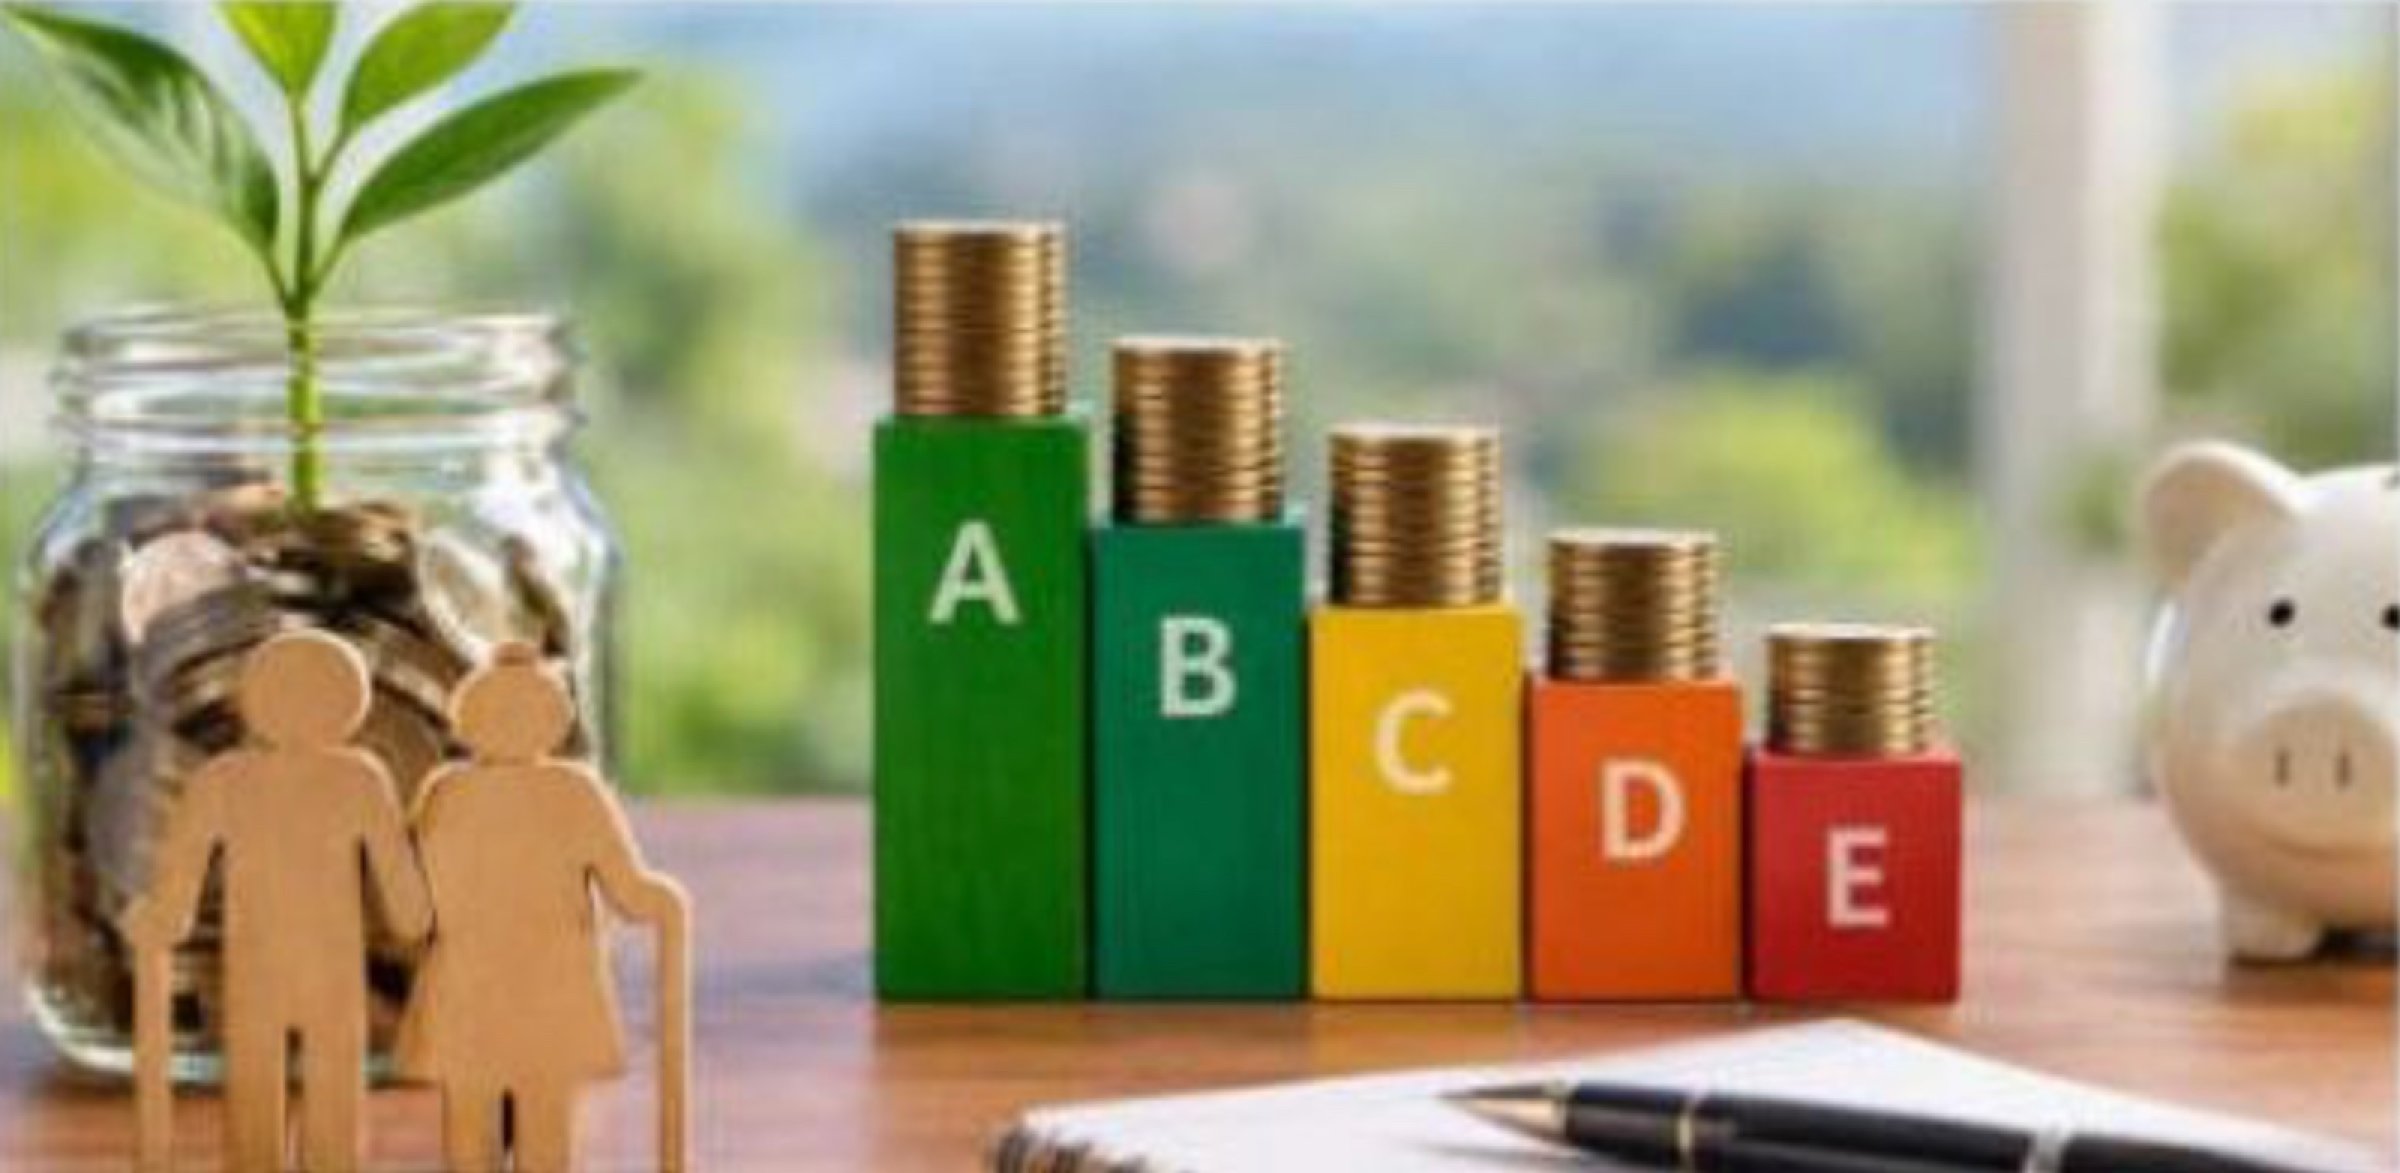
A recent move by the Pension Fund Regulatory and Development Authority (PFRDA) aims to bring greater clarity to this process. From August 28, 2026, PFRDA introduced a standardised classification and naming framework for schemes under the Multiple Scheme Framework (MSF) of the National Pension System (NPS). For NPS subscribers, the biggest change is a simple alphabet — A, B, C, D and E.
5 CATEGORIES, DIFFERENT EQUITY EXPOSURE
The new framework places MSF schemes into five categories based on their permitted equity exposure. Category A represents the highest equity exposure, at 80% to 100%. Category B covers 60% to 80%, while Category C covers 35% to 60%. Category D has 10% to 35% equity exposure, and Category E has the lowest range, from 0% to 10%.
The categories are designed to make it easier for subscribers to understand where a scheme sits on the equity-exposure spectrum. But there is an important distinction to remember: a classification is a classification, not a return promise.
HIGHER EQUITY DOES NOT MEAN HIGHER RETURNS
It can be tempting to assume that a scheme with greater equity exposure will automatically deliver better returns over time. That is not how market-linked investments work.
Equity exposure can bring greater participation in market movements, including periods of decline. A lower equity exposure does not eliminate investment risk either; it simply represents a different asset allocation.
Therefore, the A-to-E classification should be viewed as a way of understanding a scheme’s characteristics, rather than as a ranking from “better” to “worse.”
THE NAME WILL TELL YOU MORE
One practical change is that the category will become part of the scheme’s standardised name.
This may appear like a small administrative change, but it can make comparisons easier. Instead of trying to interpret different terminology used by different schemes, subscribers can identify the broad equity-exposure category more quickly.
For an investor reviewing NPS options, that is useful information to have before looking deeper into the details.
DON’T CHOOSE BY ALPHABET ALONE
While the A-to-E classification makes the first layer of comparison simpler, the alphabet cannot make the decision for you.
A subscriber should also understand the scheme’s investment approach, asset allocation, historical performance, benchmark, applicable charges and risk-related information before making a selection.
Most importantly, the choice should be considered in the context of the subscriber’s own financial objectives, investment horizon and ability to withstand fluctuations in market-linked investments.
A person with many years before retirement may experience market fluctuations differently from someone approaching retirement. The same category may therefore have a different relevance depending on the individual’s circumstances.
RETIREMENT MONEY NEEDS PERSPECTIVE
NPS is designed for long-term retirement accumulation, which makes behaviour particularly important.
Short-term market movements can sometimes create discomfort, especially when equity exposure is involved. Understanding the characteristics of the chosen scheme beforehand can help subscribers have more realistic expectations about such fluctuations.
The objective should not be to chase whichever category appears attractive at a particular point in the market cycle.
It should be to understand what the category represents and whether it is consistent with the individual’s circumstances and long-term objectives.
SIMPLER LABEL, MORE INFORMED INVESTOR
The real benefit of the new framework may be its ability to make a complex choice easier to understand.
A, B, C, D and E are only five letters, but they provide an immediate indication of equity exposure. That can encourage subscribers to look beyond names and advertisements and understand what they are actually choosing.
For investors, clarity is always a good starting point.
The new NPS classification does not remove the responsibility of understanding an investment. Instead, it gives subscribers a simpler language with which to begin that understanding.
In retirement investing, knowing what you own is not a small detail. It is the foundation of making informed choices.
(The writer, as Founder and Chief Financial Coach of Plant-Rich & Vama PlantRich, has coached 5000 plus corporate professionals in rewriting their money story)