Mohiet Hastwala
For The Goan
Over the past few months, I have noticed a growing concern among many of my friends and clients: taking care of ageing parents is becoming increasingly difficult—not only emotionally, but also financially.
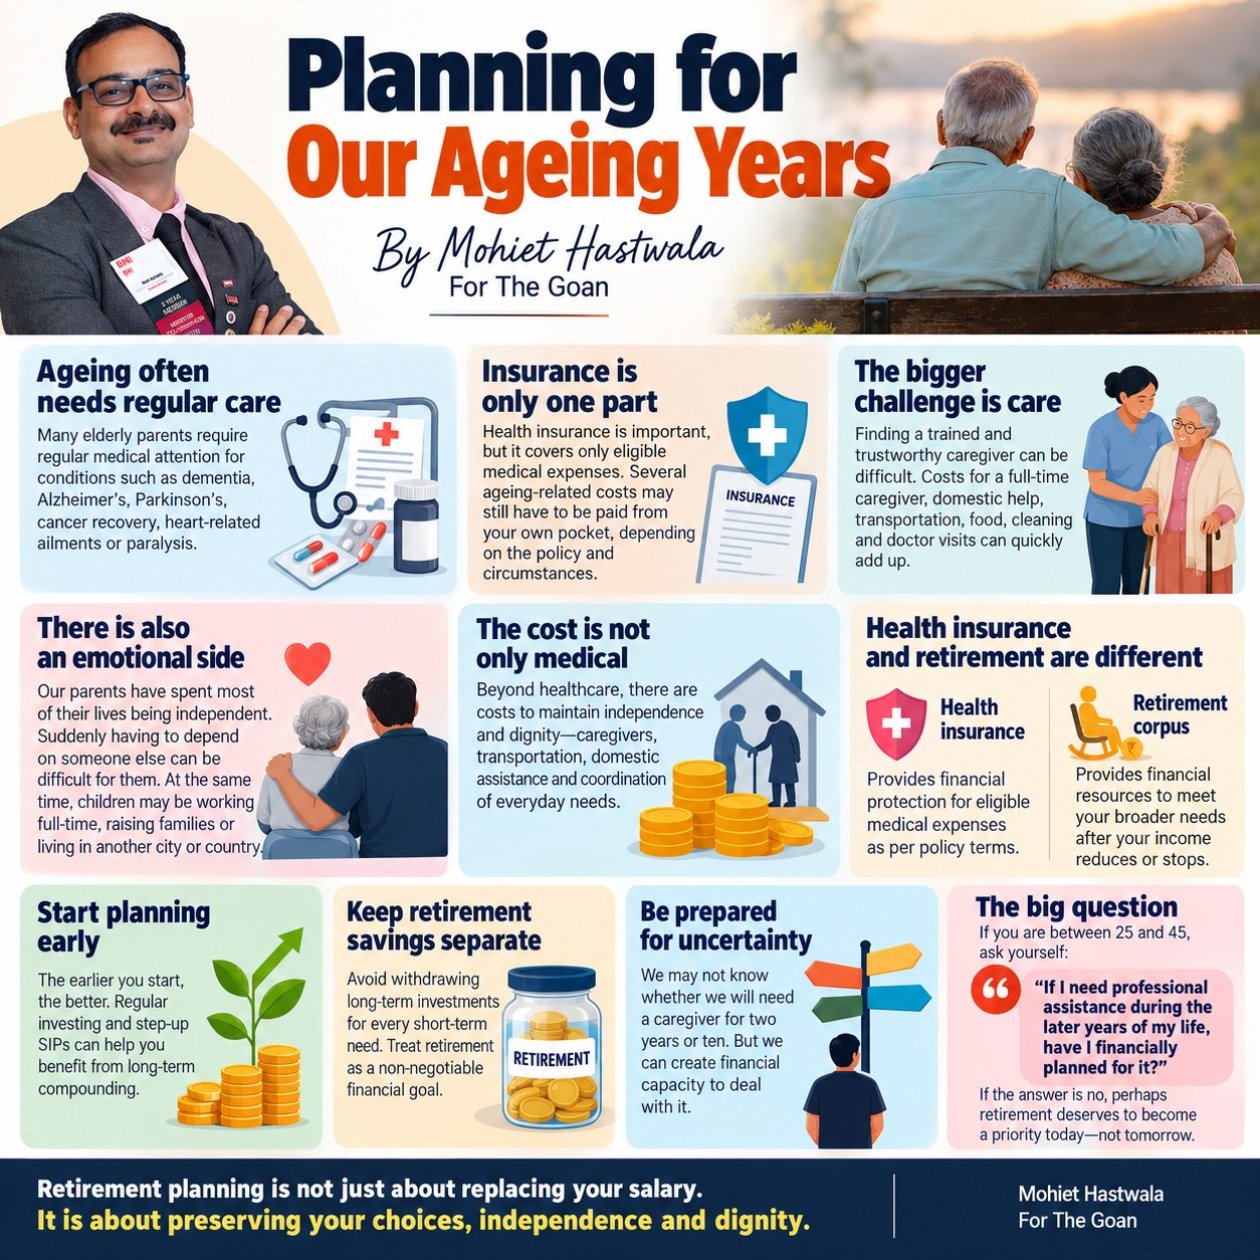
Many elderly parents today need regular medical attention because of conditions such as dementia, Alzheimer’s, Parkinson’s disease, cancer recovery, heart-related ailments or paralysis. While having health insurance is important, it addresses only one part of the problem. Several expenses associated with ageing and caregiving may still have to be paid from one’s own pocket, depending on the circumstances and policy coverage.
The bigger challenge is often care itself.
Finding a trained and trustworthy caregiver can be difficult. Depending on the level of assistance required, families may face substantial recurring costs. A full-time caregiver, domestic help, transportation, food, cleaning and assistance with doctor visits can quickly add up.
There is also an emotional dimension.
Our parents have spent most of their lives being independent. Suddenly having to depend on someone else for everyday activities can be difficult for them. At the same time, their children may be working full-time, running businesses, raising their own families or living in another city or country.
For a single child, a single parent, dual-income family or someone living overseas, coordinating the care of an elderly parent can become a second job.
The cost is not only medical
When we calculate retirement requirements, we usually consider household expenses, lifestyle, travel and healthcare. But there is another cost that deserves greater attention: the cost of maintaining independence and dignity in old age.
What if, at 70 or 75, you need someone to drive you to the doctor? What if you need assistance at home? What if your children live in another city or country? What if you need a trustworthy person to coordinate appointments, medicines or everyday requirements?
These services come at a cost.
And this is why I believe that health insurance and retirement planning should be treated as two different financial requirements.
Health insurance is designed to provide financial protection against eligible medical expenses as per the policy terms and conditions. A retirement corpus, on the other hand, provides financial resources to meet your broader needs after your active income reduces or stops.
We need to start planning for our own ageing
India has a large young working population today. But over the next two or three decades, today's 25-, 30- and 40-year-olds will themselves become senior citizens.
I will be one of them.
The question we should ask ourselves is not merely, “How much money will I need to retire?”
We should also ask:
“How much money will I need to live independently and with dignity?”
This changes the way we look at retirement planning.
A retirement corpus may eventually need to support household expenses, healthcare, caregivers, transportation, domestic assistance and other unforeseen costs. We cannot predict exactly what these expenses will be, but we can create financial capacity to deal with them.
Retirement must become a non-negotiable goal
One of the biggest mistakes I see is investors withdrawing long-term investments whenever another financial requirement arises.
A wedding comes up. A car is purchased. A business needs capital. A holiday is planned. An emergency occurs.
There is nothing wrong with using investments for genuine needs. But if retirement savings become the first source of money for every financial requirement, the retirement goal can gradually disappear.
That is why I believe retirement investing should be treated as a non-negotiable financial goal.
Investments should have a purpose. Depending on an individual's goals, risk profile and time horizon, a diversified strategy may include mutual funds, equities, NPS, fixed-income investments and other appropriate assets.
The objective should not simply be to chase the highest return.
The objective should be to build sufficient assets for the life we want to live—including the life we may need to live when we are older.
Start early, increase gradually
Someone starting at 25 or 30 has one tremendous advantage: time.
Regular investing, combined with increasing contributions as income grows, can provide an opportunity to benefit from long-term compounding. Step-up SIPs are one way investors can gradually increase their investments instead of trying to make a large commitment from day one.
Market corrections will inevitably happen. A long-term investor should understand that volatility is part of investing. Reviewing a portfolio does not necessarily mean withdrawing from it. Sometimes the most appropriate decision after a review is simply to continue investing and remain disciplined.
Prepare before you need help
We insure our homes, cars, businesses and health because we understand the financial consequences of unexpected events.
We should apply the same thinking to retirement.
We may not know whether we will need a caregiver for two years or ten. We may not know whether our children will live nearby or thousands of kilometres away. We may not know what our health will look like.
But we can prepare financially for uncertainty.
Retirement planning is not just about replacing your salary. It is about preserving your choices, independence and dignity when your earning years are behind you.
So, if you are between 25 and 45, ask yourself one question:
“If I need professional assistance during the later years of my life, have I financially planned for it?”
If the answer is no, perhaps retirement deserves to become a financial priority today—not tomorrow.